Are mortgage points worth it? A discount point costs 1% of the loan and lowers your rate, often by about a quarter of a percentage point. On a $350,000 loan, one point costs $3,500 and saves $59.41 a month in our example, so it pays for itself after 4 years 11 months. If you keep the loan longer than that, points are worth it; if you might sell or refinance sooner, they are not.
What are mortgage points?
- Discount points are prepaid interest: you pay at closing to get a lower rate for the life of the loan.
- One point = 1% of the loan amount, not of the home price.
- How much the rate drops varies by lender and by day. Many quotes are in the range of about 0.25 percentage points per point; compare the Loan Estimates you receive.
- Lender credits work the other way: a slightly higher rate in exchange for help with closing costs.
Mortgage points break-even example
$350,000, 30-year fixed, 7.40% with no points; assumes each point cuts the rate by 0.25 percentage points:
| Buy | Cost | New rate | Payment | Monthly saving | Break-even | Net after 5 years | Net after 10 years | Net over 30 years |
|---|---|---|---|---|---|---|---|---|
| 1 point | $3,500 | 7.15% | $2,363.92 | $59.41 | 4 years 11 months | $64 | $3,629 | $17,886 |
| 2 points | $7,000 | 6.90% | $2,305.10 | $118.23 | 5 years | $94 | $7,187 | $35,562 |
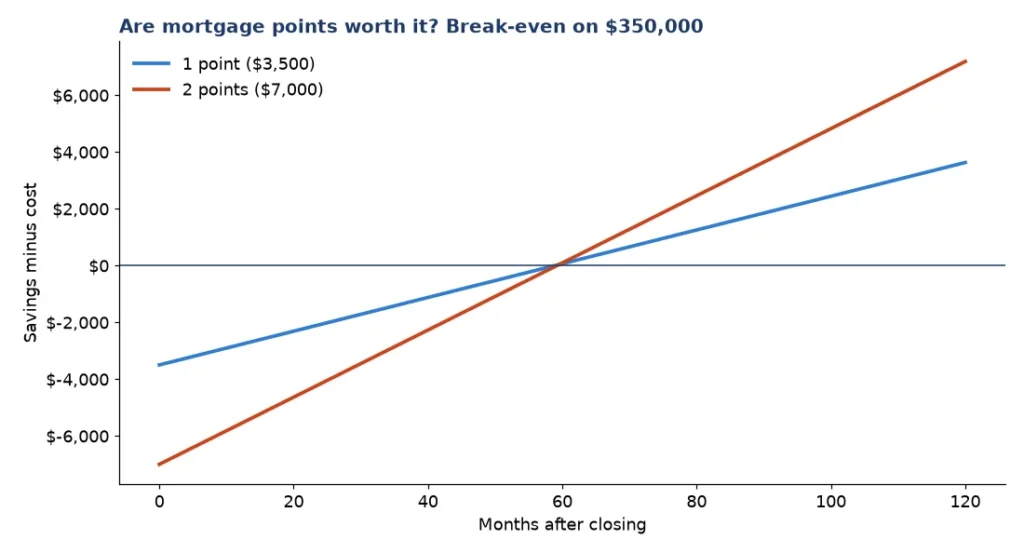
The break-even is simply the cost divided by the monthly saving. After it, every month is profit; before it, you lose money. Over the full 30 years one point nets $17,886, but most loans are paid off early when people move or refinance.
Mortgage points on different loan sizes
| Loan | One point costs | Monthly saving | Break-even |
|---|---|---|---|
| $200,000 | $2,000 | $33.95 | 4 years 11 months |
| $300,000 | $3,000 | $50.92 | 4 years 11 months |
| $500,000 | $5,000 | $84.87 | 4 years 11 months |
| $700,000 | $7,000 | $118.81 | 4 years 11 months |
The break-even barely changes with loan size, because cost and saving both scale with the loan. What changes it is how much the rate falls per point and how long you keep the loan.
The opposite: lender credits
Lender credits work in reverse: you accept a higher rate and the lender pays part of your closing costs. If 0.25 percentage points of extra rate brought a $3,500 credit on the $350,000 loan, you would pay $59.97 more a month, so the credit would be used up after 4 years 11 months. Credits make sense if you expect to move or refinance within that time, or need the cash now.
When are mortgage points worth it?
- Worth it: you expect to keep the loan well past the break-even (here about 4 years 11 months), you have spare cash after the down payment and reserves, and rates are not expected to fall soon.
- Not worth it: you may move or refinance within a few years, the cash would push your down payment below 20% and add PMI, or you need the money for reserves.
- Compare: the same $3,500 put toward the down payment lowers the loan and the payment too. Run both with the mortgage calculator.
Are mortgage points tax deductible?
Under IRS rules, points paid to buy your main home can generally be deducted in the year you pay them if you itemize and meet the conditions in Publication 936. Points on a refinance are usually deducted over the life of the loan. Most taxpayers take the standard deduction, so check whether itemizing applies to you.
Points when you refinance
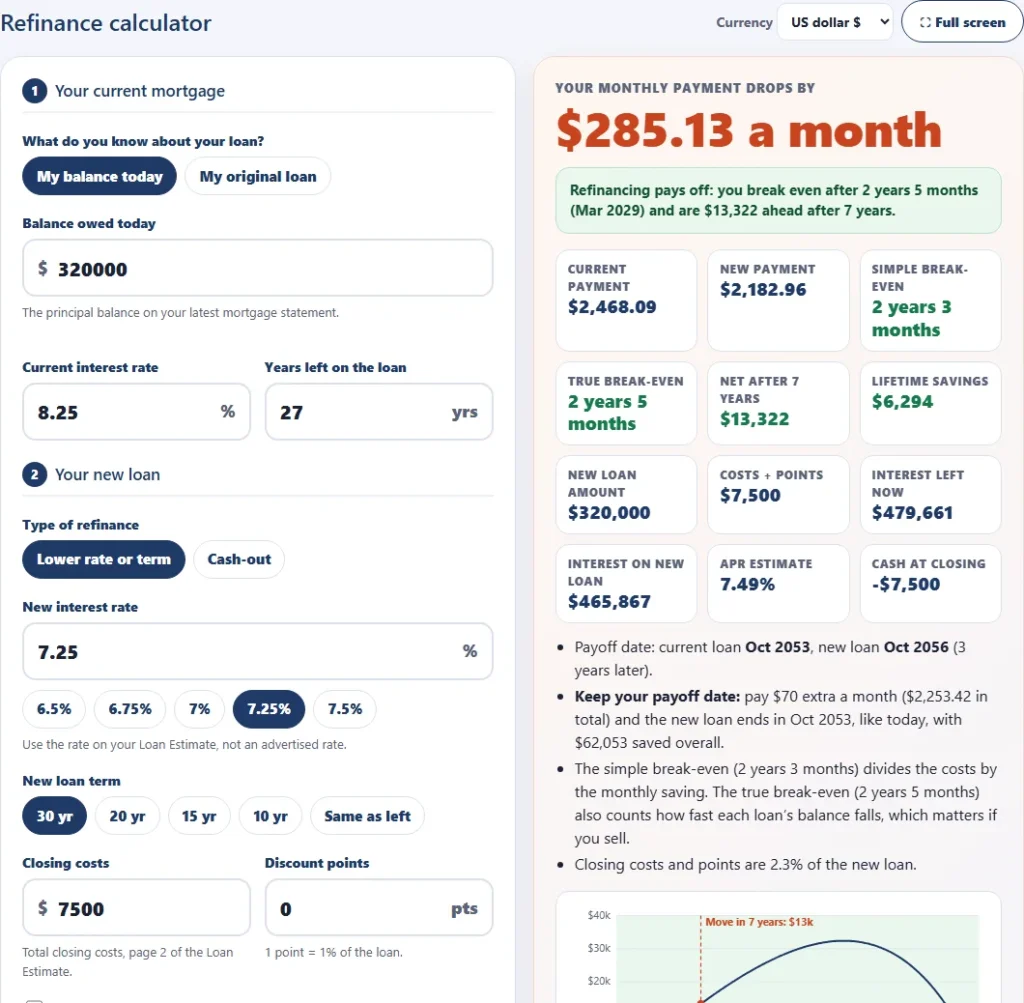
The same break-even logic applies, added to the refinance closing costs. The refinance calculator includes points and shows the true break-even month.
These examples explain the math for planning. They are general information, not financial advice; your lender’s Loan Estimate gives the real figures.
Related calculators and guides
- Mortgage calculator
- Refinance calculator
- Closing cost calculator
- 15 vs 30 year mortgage
- how much house can I afford
Sources
- Primary Mortgage Market Survey (Freddie Mac): 30-year fixed 7.40% on October 15, 2026
- Publication 936, Home Mortgage Interest Deduction: points (IRS)
- Loan Estimate explainer: points and lender credits (CFPB)
Frequently asked questions
5 quick answers
Are mortgage points worth it?
Only if you keep the loan past the break-even. In the example, one point breaks even after 4 years 11 months.
How much does one mortgage point lower the rate?
It varies by lender; about 0.25 percentage points is a common quote. Compare Loan Estimates.
How much is one point on a $350,000 mortgage?
$3,500, which is 1% of the loan amount.
Can I deduct mortgage points?
Often yes for a home purchase if you itemize (IRS Publication 936). Refinance points are usually spread over the loan term.
Should I buy points or put more down?
More down lowers the loan and may remove PMI; points lower the rate. Compare both payments, and keep enough cash in reserve.
Did you like this?
Last updated: