A mortgage calculator estimates your monthly home loan payment from the home price, down payment, interest rate and loan term. This free mortgage calculator also adds property tax, home insurance, HOA fees and PMI, shows what extra payments save, and prints a year-by-year amortization table.
Quick answer: Monthly mortgage payment = L × r ÷ (1 − (1 + r)−n), where L is the loan amount, r the monthly interest rate and n the number of payments. A $320,000 loan at 6.5% for 30 years costs $2,022.62 a month in principal and interest. Add $366.67 property tax and $150.00 insurance and the payment is $2,539.29.
How to use this mortgage calculator, step by step
Type the home price into the mortgage calculator, choose a down payment as a percent or an amount, then add the interest rate and the term. The answer updates as you type, so there is no Calculate button. Open the taxes, insurance, HOA and PMI boxes to see the real monthly cost, not only the loan payment.
- Pick your country; it sets the compounding rule and the options.
- Enter the home price, down payment, rate and term. The rate shown is an editable example, not a quote.
- Add property tax, insurance, HOA fees and PMI if they apply.
- Try an extra monthly payment, then copy the result or the link.
| Input | What it means | Typical value |
|---|---|---|
| Down payment | Cash you pay up front; the rest is the loan | 3% to 25% of the price |
| Interest rate | The yearly rate on the loan, before fees | Check your lender |
| Property tax | Yearly tax as a percent of the home price | 0.5% to 2%, depends on location |
| Home insurance | Yearly premium for the home | $1,000 to $3,000 a year in many US areas |
| PMI | Mortgage insurance when you put down under 20% | 0.3% to 1.5% of the loan a year |
| Extra payment | Money added to every payment, all of it to principal | $0 to $1,000 a month |
Mortgage payment calculator: the formula explained
A mortgage is an amortizing loan: every payment is the same size, but the share that pays interest shrinks and the share that pays down the balance grows. The mortgage payment calculator uses the standard annuity formula, the same one lenders use.
Formula: M = L × r ÷ (1 − (1 + r)−n). M is the monthly payment, L the loan amount, r the yearly rate ÷ 12 and n the number of monthly payments (years × 12).
Example 1: $400,000 home, 20% down, 6.5%, 30 years
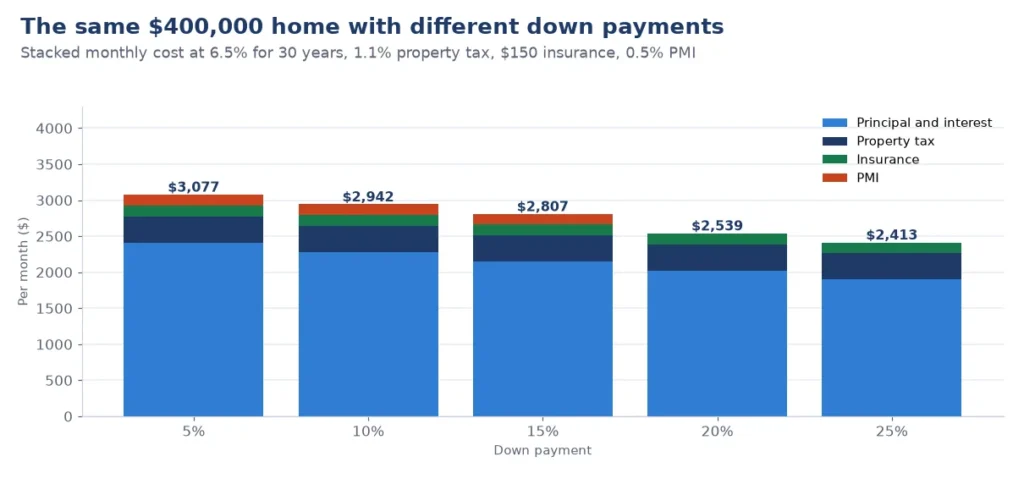
The down payment is $80,000, so the loan is $320,000. The monthly rate is 6.5% ÷ 12 = 0.54167% and n = 360. The payment is $2,022.62 a month, so you repay $728,142 over 30 years and $408,142 of that is interest. With a property tax of 1.1% a year ($366.67 a month) and insurance of $1,800 a year ($150.00 a month), the total is $2,539.29. The mortgage calculator opens on this example.
Example 2: the same home with 10% down and PMI
With $40,000 down the loan is $360,000 and the payment rises to $2,275.44. Because the down payment is under 20%, PMI of 0.5% a year adds $150.00 a month, so the total is $2,942.11. The PMI stops when the balance reaches 80% of the price ($320,000), after about 7 years 11 months.
Monthly mortgage payment per 0,000 borrowed
This lookup table gives the principal and interest payment for every $100,000 of loan. Multiply by your loan size ÷ 100,000: a $320,000 loan at 6.5% for 30 years is 3.2 × $632.07 = $2,022.62.
| Rate | 15 years | 20 years | 25 years | 30 years |
|---|---|---|---|---|
| 4% | $739.69 | $605.98 | $527.84 | $477.42 |
| 5% | $790.79 | $659.96 | $584.59 | $536.82 |
| 5.5% | $817.08 | $687.89 | $614.09 | $567.79 |
| 6% | $843.86 | $716.43 | $644.30 | $599.55 |
| 6.5% | $871.11 | $745.57 | $675.21 | $632.07 |
| 7% | $898.83 | $775.30 | $706.78 | $665.30 |
| 8% | $955.65 | $836.44 | $771.82 | $733.76 |
Mortgage calculator with taxes and insurance (PITI)
Lenders quote principal and interest, but you pay PITI: principal, interest, taxes and insurance, often collected in an escrow account. This mortgage calculator with taxes adds them so the number matches your real budget.
Property tax is a percent of the home value each year: a $400,000 home at 1.1% costs $4,400 a year, or $366.67 a month. The table shows how much the rate matters. In the United States property taxes may be deductible within limits; see the IRS page on deductible taxes.
| Property tax rate | Tax a year on $400,000 | Tax a month | Total monthly payment (with $150 insurance) |
|---|---|---|---|
| 0.5% | $2,000 | $166.67 | $2,339.29 |
| 1% | $4,000 | $333.33 | $2,505.95 |
| 1.5% | $6,000 | $500.00 | $2,672.62 |
| 2% | $8,000 | $666.67 | $2,839.29 |
Add HOA or condo fees as a monthly amount. They do not change the loan, but lenders count them when they judge what you can afford.
Mortgage calculator with PMI: what it costs and when it ends
In the United States, lenders usually require private mortgage insurance (PMI) when the down payment is under 20%. It protects the lender, not you. A typical charge is 0.3% to 1.5% of the loan a year, higher for smaller down payments and lower credit scores. Under the US Homeowners Protection Act, PMI on a conventional loan can be canceled on request at 80% of the original value and ends automatically at 78%. The mortgage calculator with PMI drops it when the balance reaches 80% of the price.
| Down payment | Cash down | Loan | Principal and interest | PMI at 0.5% a year (monthly cost) | PMI lasts about |
|---|---|---|---|---|---|
| 5% | $20,000 | $380,000 | $2,401.86 | $158.33 | 10 years 4 months |
| 10% | $40,000 | $360,000 | $2,275.44 | $150.00 | 7 years 11 months |
| 15% | $60,000 | $340,000 | $2,149.03 | $141.67 | 4 years 8 months |
Outside the US, the same idea has other names. Canada uses mortgage default insurance and Australia uses lenders mortgage insurance (LMI), and both are usually one-time premiums that can be added to the loan. Use the upfront premium box for those.
Extra payment mortgage calculator: pay off your mortgage sooner
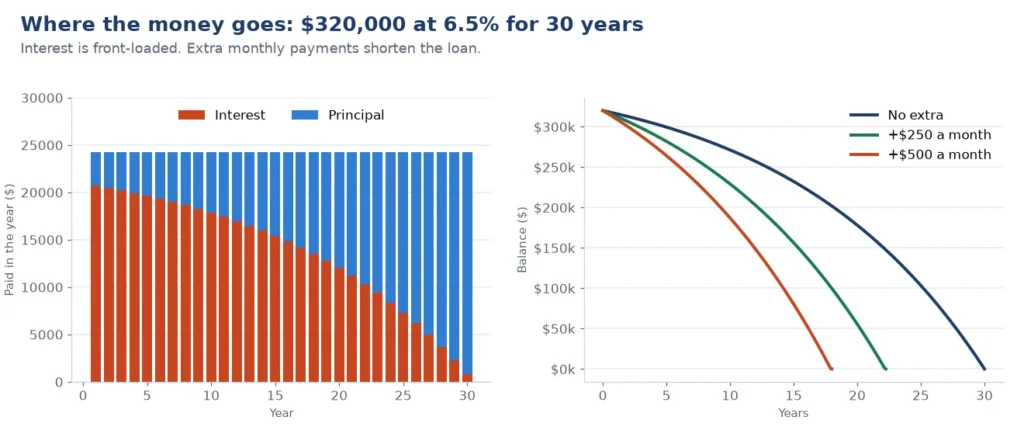
Every dollar of extra payment goes straight to principal, so it stops accruing interest for the rest of the loan. The extra payment mortgage calculator shows the time and interest saved. On the $320,000 loan at 6.5%, these extras change the outcome:
| Extra a month | Principal and interest paid | Paid off in | Time saved | Total interest | Interest saved |
|---|---|---|---|---|---|
| None | $2,022.62 | 30 years | – | $408,142 | – |
| $100 | $2,122.62 | 26 years 2 months | 3 years 10 months | $346,444 | $61,698 |
| $250 | $2,272.62 | 22 years 3 months | 7 years 9 months | $285,148 | $122,994 |
| $500 | $2,522.62 | 18 years | 12 years | $222,590 | $185,552 |
Extra payments help most early in the loan, so run the mortgage calculator with a few amounts, because the balance, and the interest on it, is largest then. A one-time lump sum works the same way, and so does a bi-weekly plan: paying half the monthly amount every two weeks makes 26 half payments, which equals 13 monthly payments a year. Check your loan for a prepayment penalty first.
Mortgage amortization calculator: the schedule by year
The mortgage amortization calculator shows principal, interest and the balance left each year. Interest is front-loaded: in year one of the example, $20,695 of the $24,271 you pay is interest. By year 30 almost all of it is principal.
| Year | Principal paid | Interest paid | Balance at year end |
|---|---|---|---|
| 1 | $3,577 | $20,695 | $316,423 |
| 5 | $4,636 | $19,636 | $299,555 |
| 10 | $6,410 | $17,861 | $271,284 |
| 15 | $8,864 | $15,407 | $232,189 |
| 20 | $12,257 | $12,014 | $178,129 |
| 25 | $16,949 | $7,322 | $103,373 |
| 30 | $23,438 | $833 | $0 |
The tool prints every year for your own numbers. After 15 years of this example you still owe $232,189, about 73% of the loan.
15-year vs 30-year mortgage on the same loan
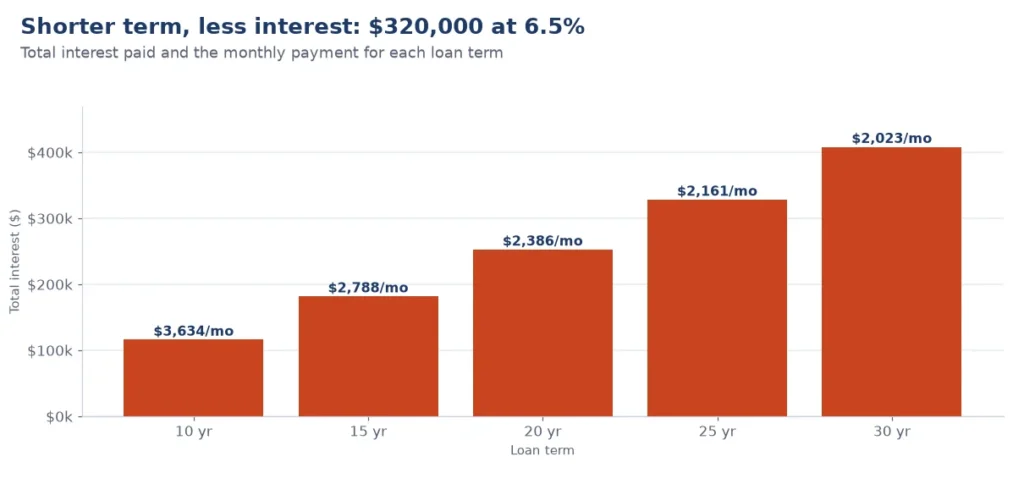
A shorter term means a higher payment but far less interest, so try both in the mortgage calculator. This table keeps the rate at 6.5% so only the term changes (in practice 15-year loans often carry a lower rate, which widens the gap).
| Term | Monthly payment | Total interest | Total repaid |
|---|---|---|---|
| 10 years | $3,633.54 | $116,024 | $436,024 |
| 15 years | $2,787.54 | $181,758 | $501,758 |
| 20 years | $2,385.83 | $252,600 | $572,600 |
| 30 years | $2,022.62 | $408,142 | $728,142 |
Mortgage calculator Canada: semi-annual compounding
Canadian lenders quote fixed rates compounded semi-annually, not monthly, and the Interest Act sets how a mortgage rate must be stated (section 6). Variable rates are usually compounded monthly. Choose Canada in the mortgage calculator Canada setting and it converts the quoted rate: effective monthly rate = (1 + rate ÷ 2)1/6 − 1. A typical amortization is 25 years; confirm the current maximum with your lender.
Example: a $450,000 home with 20% down gives a $360,000 mortgage at 5% for 25 years. With semi-annual compounding the payment is $2,093.78 a month, compared with $2,104.52 if the same 5% were compounded monthly. Accelerated bi-weekly payments of $1,046.89 every two weeks clear the loan in about 21 years 6 months instead of 25 years and cut interest from $268,133 to $224,620.
Mortgage default insurance premiums in Canada
With less than 20% down, Canadian mortgages must be insured. The premium is a percent of the loan, added to the mortgage. These are the standard CMHC rates for a 25-year amortization (check CMHC for the current table). A borrowed or gifted down payment in the 5% to 9.99% band costs 4.50%, and a 30-year amortization (open to first-time buyers and new builds since December 15, 2024) adds 0.20%. Homes priced at $1.5 million or more need 20% down.
| Down payment | Loan-to-value | Premium added to the loan |
|---|---|---|
| 5% to 9.99% | 90.01% to 95% | 4.00% |
| 10% to 14.99% | 85.01% to 90% | 3.10% |
| 15% to 19.99% | 80.01% to 85% | 2.80% |
| 20% or more | 80% or less | none |
For example, 5% down on a $500,000 home is a $475,000 loan plus a 4% premium of $19,000, so you borrow $494,000 and pay $2,873.13 a month at 5% over 25 years. Type 4 in the upfront premium box to reproduce it.
Mortgage repayment calculator for the UK
In the UK, a mortgage repayment calculator compares two types. A repayment mortgage pays interest and capital every month and clears the debt by the end of the term. An interest-only mortgage pays only the interest, so the full loan is still owed at the end and you need a plan to repay it. Choose UK, then tick Interest-only to compare. The currency box switches the symbol to pounds. UK property tax (council tax) is separate, so set property tax to 0.
| £250,000 at 4.5% over 25 years | Monthly payment | Total interest | Owed at the end |
|---|---|---|---|
| Repayment | £1,389.58 | £166,874 | £0 |
| Interest-only | £937.50 | £281,250 | £250,000 |
Many UK deals are fixed for two to five years, so rerun the mortgage repayment calculator when your rate changes.
Australia and New Zealand: principal and interest
Australian home loans are usually principal-and-interest (P&I) loans, with monthly, fortnightly or weekly repayments, over up to 30 years, with a variable or fixed rate. If the deposit is under 20%, the lender may charge lenders mortgage insurance, see lenders mortgage insurance. Moneysmart, the government money guide, has its own mortgage calculator and notes that offset accounts can cut the interest you pay.
Example: an A$800,000 home with a 20% deposit is a $640,000 loan. At 6.2% over 30 years the repayment is $3,919.80 a month and total interest is $771,129.
How much house can I afford? A rule of thumb
A common guideline keeps housing costs (the full PITI plus HOA) near 28% of gross monthly income and all debt payments near 36%. Run your income through the table, then use the mortgage calculator to find the price that fits your budget.
| Gross income a year | Monthly income | Housing budget at 28% | All debts at 36% |
|---|---|---|---|
| $60,000 | $5,000 | $1,400 | $1,800 |
| $90,000 | $7,500 | $2,100 | $2,700 |
| $120,000 | $10,000 | $2,800 | $3,600 |
| $180,000 | $15,000 | $4,200 | $5,400 |
Common mortgage mistakes and tips
- Looking only at principal and interest. Taxes, insurance, HOA and PMI can add 25% or more to the payment.
- Ignoring closing costs. Budget for them in addition to the down payment; they are not part of this estimate.
- Comparing only the monthly payment. A longer term lowers the payment but raises total interest, so compare both numbers.
- Using an old rate. Rates change weekly. The Freddie Mac Primary Mortgage Market Survey shows the current national average to compare with your quote.
- Forgetting rate changes. Adjustable and variable-rate mortgages reset, so test a higher rate.
Any mortgage calculator gives an estimate for planning, not financial advice or a loan offer. Your lender sets the final figures.
Questions people ask about mortgage payments
How much is a $300,000 mortgage per month?
A $300,000 mortgage costs about $1,896.20 a month in principal and interest at 6.5% over 30 years, or $2,613.32 over 15 years. Taxes and insurance come on top.
How much can I borrow for a given monthly payment?
Divide the payment by the figure per $100,000 in the table above, then multiply by 100,000. A $2,000 payment at 6.5% over 30 years supports about $316,422 of principal and interest.
Mortgage calculator for refinance: what changes?
Enter the remaining balance as the home price with no down payment, plus the new rate and term. Compare the payment and total interest with your current loan, then subtract closing costs from the savings.
Frequently asked questions
8 quick answers
How do you calculate a monthly mortgage payment?
Use M = L × r ÷ (1 − (1 + r)^−n), where L is the loan, r the yearly rate ÷ 12 and n the number of months. For $320,000 at 6.5% over 30 years that is $2,022.62 before taxes and insurance.
How much is the monthly payment on a $400,000 mortgage?
A $400,000 loan costs $2,528.27 a month at 6.5% over 30 years, principal and interest only. With 20% down on a $400,000 home, the loan is $320,000 and the payment is $2,022.62.
Does this mortgage calculator include property tax and insurance?
Yes. Enter the yearly tax rate, the insurance premium and any HOA fees, and the total monthly payment includes them. Set them to 0 to see principal and interest only.
When do I have to pay PMI?
In the US, lenders usually charge PMI when the down payment is under 20%. It can be canceled at 80% of the original value and ends automatically at 78%.
How much does an extra payment save?
On a $320,000 loan at 6.5% over 30 years, an extra $250 a month saves about $122,994 in interest and shortens the loan by 7 years 9 months.
Is a 15-year or 30-year mortgage better?
A 15-year loan has a higher payment but costs far less interest. On $320,000 at 6.5% it saves about $226,385. Choose the term whose payment you can afford comfortably.
What is the mortgage payment calculator formula in Excel?
Use =PMT(rate/12, years*12, -loan). For $320,000, =PMT(0.065/12, 360, -320000) returns $2,022.62.
Does the mortgage calculator show an amortization schedule?
Yes. It lists principal, interest and the remaining balance for every year, and it updates when you add extra payments.
Related calculators
- Loan calculator for personal and student loans
- Car loan calculator with trade-in and sales tax
- Compound interest calculator for savings growth
- Simple interest calculator
- Percentage calculator
- All calculators and money worksheets for practice
Sources and further reading
- Moneysmart (Australian Government): mortgage calculator
- Wikipedia: mortgage loan
- Justice Laws Website (Canada): Interest Act
- Freddie Mac: Primary Mortgage Market Survey
Last updated: October 2026.