How much down payment for a house do you need? Less than most people think: 3% on some conventional loans, 3.5% with an FHA loan, and nothing with a VA or USDA loan. Putting 20% down avoids PMI and lowers the payment. On a $350,000 home, 20% is $70,000; 3.5% is $12,250. Here is what each down payment costs per month, and how long it takes to save.
Minimum down payment by loan type
| Loan type | Minimum down payment | Notes |
|---|---|---|
| Conventional (Fannie Mae HomeReady and similar) | 3% | Up to 97% loan-to-value for eligible buyers; PMI until 20% equity |
| FHA | 3.5% | Annual mortgage insurance (0.55% for most) plus an upfront premium |
| VA | 0% | For eligible service members and veterans; no PMI |
| USDA guaranteed | 0% | Eligible rural areas, income limits apply; guarantee fees |
| Conventional, no PMI | 20% | The traditional target |
Credit score and down payment
Your credit score decides which of these low down payments you can use. FHA is the most forgiving: the rules allow 3.5% down with a score of 580 or higher, but require 10% down for scores from 500 to 579. Conventional loans usually need at least 620. VA and USDA loans have no minimum score in the program rules, but most lenders set their own.
| Loan type | Typical minimum score | Down payment at that score |
|---|---|---|
| FHA | 580 | 3.5% |
| FHA | 500 to 579 | 10% |
| Conventional | 620 | 3% to 5%, more with a lower score |
| VA | No program minimum (lenders often ask for 620) | 0% |
| USDA | No program minimum (lenders often ask for 640) | 0% |
A higher score also lowers the cost of a small down payment: PMI on a conventional loan is priced by score, so the same 5% down can cost much less a month at 760 than at 640.
What each option costs per month
$350,000 home, 30-year fixed at 7.40%, with example property tax, insurance and PMI:
| Down payment | Cash down | Loan | Principal + interest | PMI | Total monthly |
|---|---|---|---|---|---|
| 3% | $10,500 | $339,500 | $2,351 | $141 | $2,963 |
| 3.5% | $12,250 | $337,750 | $2,339 | $141 | $2,950 |
| 5% | $17,500 | $332,500 | $2,302 | $139 | $2,912 |
| 10% | $35,000 | $315,000 | $2,181 | $131 | $2,783 |
| 20% | $70,000 | $280,000 | $1,939 | $0 | $2,409 |
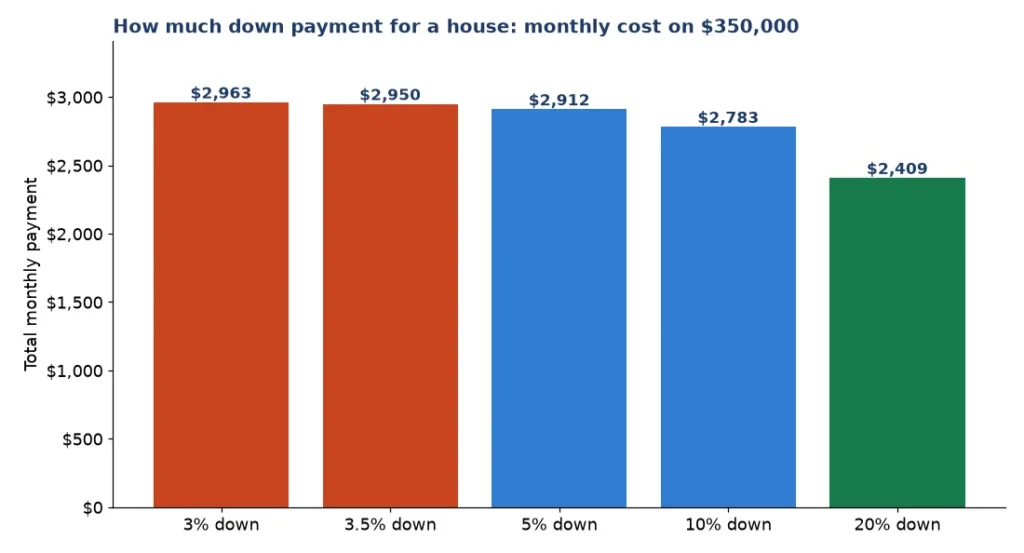
Going from 3.5% to 20% down cuts the principal, interest and PMI by $541 a month on this home, but needs $57,750 more cash. The PMI part can be removed later; see how to get rid of PMI.
Down payment by home price
| Home price | 3% | 3.5% | 5% | 10% | 20% |
|---|---|---|---|---|---|
| $200,000 | $6,000 | $7,000 | $10,000 | $20,000 | $40,000 |
| $250,000 | $7,500 | $8,750 | $12,500 | $25,000 | $50,000 |
| $300,000 | $9,000 | $10,500 | $15,000 | $30,000 | $60,000 |
| $400,000 | $12,000 | $14,000 | $20,000 | $40,000 | $80,000 |
| $500,000 | $15,000 | $17,500 | $25,000 | $50,000 | $100,000 |
| $600,000 | $18,000 | $21,000 | $30,000 | $60,000 | $120,000 |
Is a 20 percent down payment necessary?
- No. Most loans allow far less. Waiting years to save 20% can cost more than PMI if prices or rents rise meanwhile.
- But 20% helps: no PMI on a conventional loan, a smaller loan, a lower payment and more equity if prices fall.
- Do not empty your savings. Keep money for closing costs, moving and an emergency fund.
How long will it take to save?
| Saving | 3.5% ($12,250) | 10% ($35,000) | 20% ($70,000) |
|---|---|---|---|
| $500 a month | 2 years 1 month | 5 years 10 months | 11 years 8 months |
| $1,000 a month | 1 year 1 month | 2 years 11 months | 5 years 10 months |
| $1,500 a month | 9 months | 2 years | 3 years 11 months |
Before interest on savings. Down payment assistance programs and gifts from family can shorten this; FHA allows gifts for the down payment.
Cash to close: more than the down payment
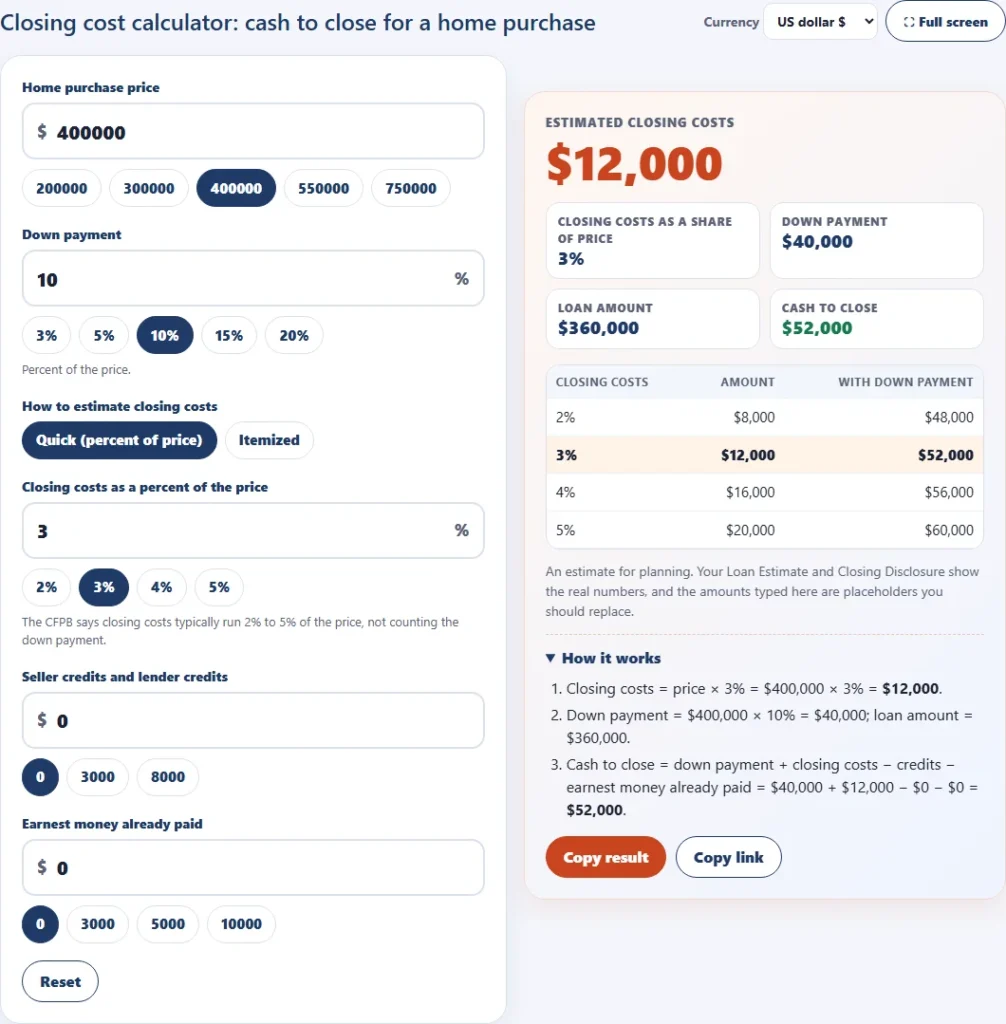
You also pay closing costs, which commonly run a few percent of the loan, plus prepaid items such as insurance and property tax escrow. Estimate them with the closing cost calculator, and check the total “cash to close” on your Loan Estimate.
To see what price your income supports, read how much house can I afford, then try the mortgage calculator.
These examples explain the math for planning. They are general information, not financial advice; your lender’s Loan Estimate gives the real figures.
Related calculators and guides
- Mortgage calculator
- Closing cost calculator
- how much house can I afford
- how to get rid of PMI
- are mortgage points worth it
Sources
- Minimum down payment for FHA (HUD): 3.5% minimum
- Mortgagee Letter 2023-05, annual MIP reduction (HUD)
- VA-backed home loans (U.S. Department of Veterans Affairs): no down payment for most VA-backed loans
- Single Family Housing Guaranteed Loan Program (USDA): 100% financing in eligible areas
- HomeReady low down payment mortgage (Fannie Mae): 3% down
- Primary Mortgage Market Survey (Freddie Mac)
Frequently asked questions
5 quick answers
How much down payment do you need for a house?
As little as 3% on some conventional loans, 3.5% for FHA and 0% for VA or USDA loans. 20% avoids PMI on a conventional loan.
What is the down payment on a $350,000 house?
$10,500 at 3%, $12,250 at 3.5%, $35,000 at 10% and $70,000 at 20%.
Is it better to put 20% down?
It lowers the payment and avoids PMI, but not at the cost of your emergency fund. Compare the monthly difference with the extra cash needed.
Can a down payment be a gift?
Yes, many loan types including FHA allow gifts from family; lenders will ask for a gift letter.
Do first-time buyers need 20% down?
No. Many first-time buyers put down 3% to 5% or use FHA, VA or USDA loans.
Did you like this?
Last updated: