A HELOC calculator answers two questions: how much a home equity line of credit lets you borrow, and what the payments look like once you do. Enter your home value, mortgage balance and the lender's limit for the first answer, or the amount, rate and terms for the second.
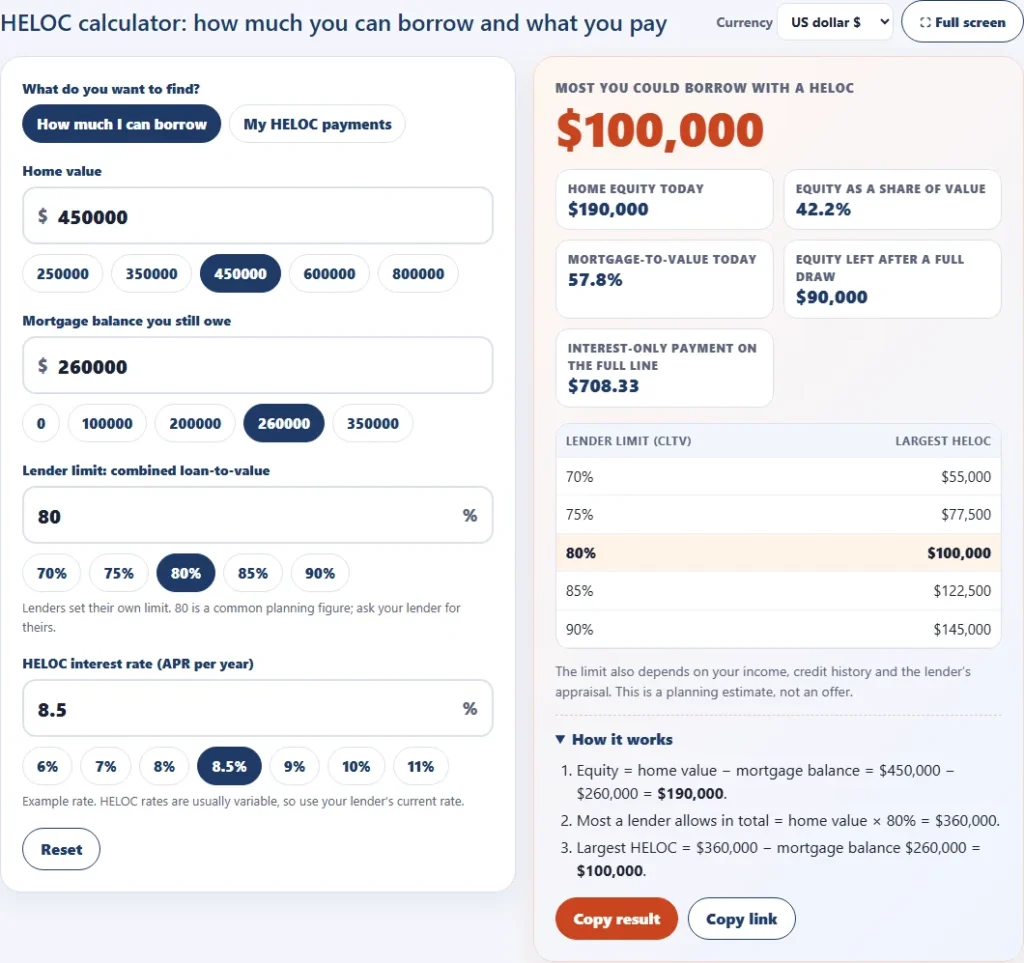
Quick answer: Largest HELOC = home value × lender's combined loan-to-value limit − mortgage balance. A $450,000 home with a $260,000 mortgage and an 80% limit allows $100,000. Borrow $60,000 at 8.5% and the interest-only payment is $425 a month.
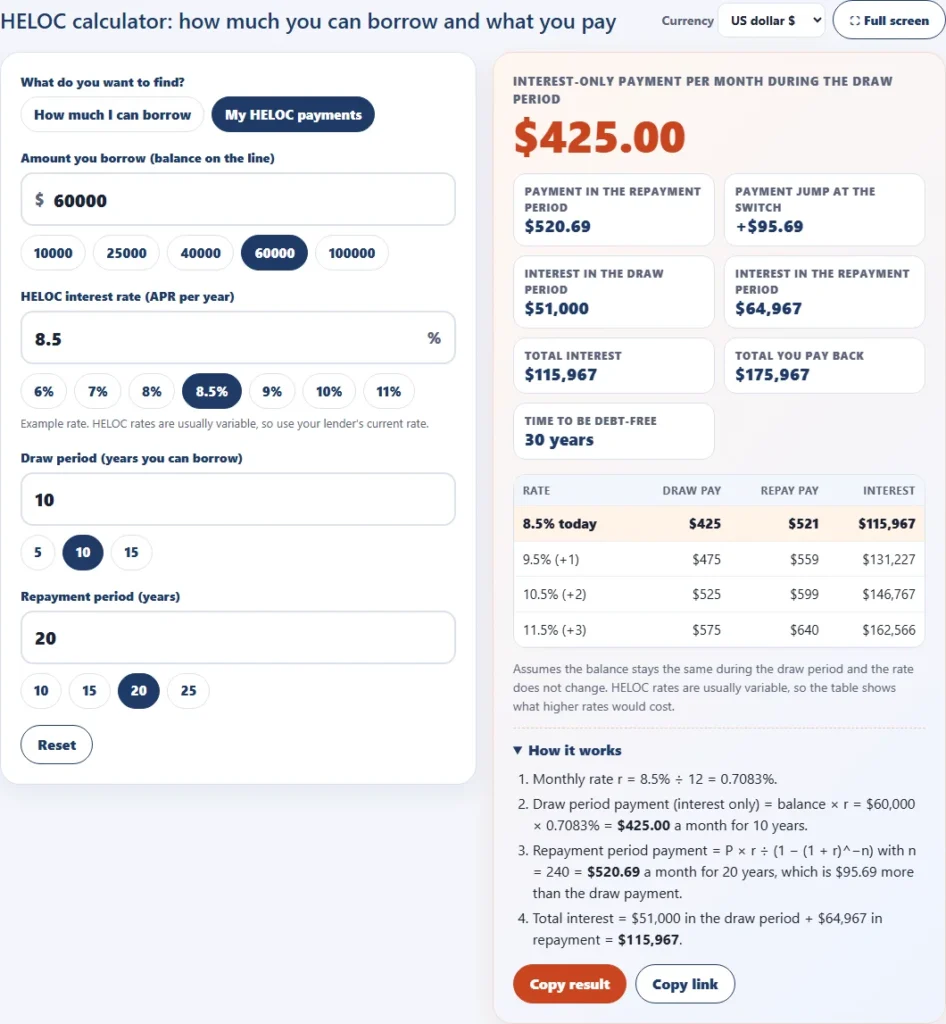
How to use the HELOC calculator
- Choose How much I can borrow to find your credit line, or My HELOC payments to see what a balance costs.
- For the limit, enter the home value, the mortgage balance you still owe, and the lender's combined loan-to-value limit. If you do not know it, 80% is a common planning figure.
- For payments, enter the amount you borrow, the interest rate, the draw period and the repayment period. The default rate is only an example, so use your lender's current rate.
- Read the interest-only payment, the repayment payment, the jump between them and the total interest.
- Check the rate table to see how the payments change if a variable rate rises by one to three points.
This calculator runs in your browser and keeps your numbers on your device. It is a planning tool, not an offer of credit, and it does not replace the disclosures a lender must give you.
Home equity line of credit calculator: how a HELOC works
This home equity line of credit calculator follows the way the Federal Trade Commission describes a HELOC: a revolving line of credit, similar to a credit card, except it is secured by your home. You make payments only on the amount you borrow, not the full amount available, and the line typically has a variable rate.
So there are two numbers worth knowing before you apply. The first is the size of the line you could qualify for, which depends on your equity. The second is what each stage of the loan costs per month, which is what the HELOC calculator's payment mode works out.
How much can I borrow with a HELOC?
The Consumer Financial Protection Bureau explains that a HELOC lets you borrow against the equity in your home, which is the value of the home minus what you owe on your mortgage. Lenders do not lend all of it. They set a limit on the total of your mortgage and the new line, usually written as a percentage of the home's value and called the combined loan-to-value ratio.
- Equity = home value − mortgage balance.
- Total allowed = home value × the lender's limit.
- Largest HELOC = total allowed − mortgage balance.
The FTC notes in its home equity guidance that many lenders prefer that you borrow no more than 80 percent of the equity in your home, and that the amount you can borrow also depends on your income, your credit history and the market value of the home. The table shows how the limit changes the answer for a $450,000 home with a $260,000 mortgage.
| Lender limit (CLTV) | Total debt allowed | Largest HELOC |
|---|---|---|
| 70% | $315,000 | $55,000 |
| 75% | $337,500 | $77,500 |
| 80% | $360,000 | $100,000 |
| 85% | $382,500 | $122,500 |
| 90% | $405,000 | $145,000 |
HELOC limit by home value and mortgage balance
The table below uses an 80% limit. Find your home value across the top and your mortgage balance down the side. Zero means the mortgage already uses up the limit.
| Mortgage balance | $250,000 | $350,000 | $450,000 | $600,000 | $800,000 |
|---|---|---|---|---|---|
| $0 | $200,000 | $280,000 | $360,000 | $480,000 | $640,000 |
| $100,000 | $100,000 | $180,000 | $260,000 | $380,000 | $540,000 |
| $200,000 | $0 | $80,000 | $160,000 | $280,000 | $440,000 |
| $300,000 | $0 | $0 | $60,000 | $180,000 | $340,000 |
| $400,000 | $0 | $0 | $0 | $80,000 | $240,000 |
| $500,000 | $0 | $0 | $0 | $0 | $140,000 |
HELOC payment calculator: the draw period and the repayment period
The HELOC draw period is the first of two phases. The CFPB says you can generally borrow up to your credit limit during the draw period, which could last 10 years, for example. After it ends you can no longer borrow and you enter the repayment period, which the CFPB says is often over ten or 20 years, with monthly payments that are often significantly higher.
- Draw period payment = balance × (annual rate ÷ 12) when the plan is interest-only.
- Repayment payment = P × r ÷ (1 − (1 + r)−n), where r is the monthly rate and n is the number of months.
- Payment jump = repayment payment − interest-only payment.
| Balance | Rate | Interest-only payment | 10-year repayment | 15-year repayment | 20-year repayment |
|---|---|---|---|---|---|
| $25,000 | 8.5% | $177.08 | $309.96 | $246.18 | $216.96 |
| $50,000 | 8.5% | $354.17 | $619.93 | $492.37 | $433.91 |
| $75,000 | 8.5% | $531.25 | $929.89 | $738.55 | $650.87 |
| $100,000 | 8.5% | $708.33 | $1,239.86 | $984.74 | $867.82 |
| $50,000 | 10.5% | $437.50 | $674.67 | $552.70 | $499.19 |
HELOC interest only payment calculator
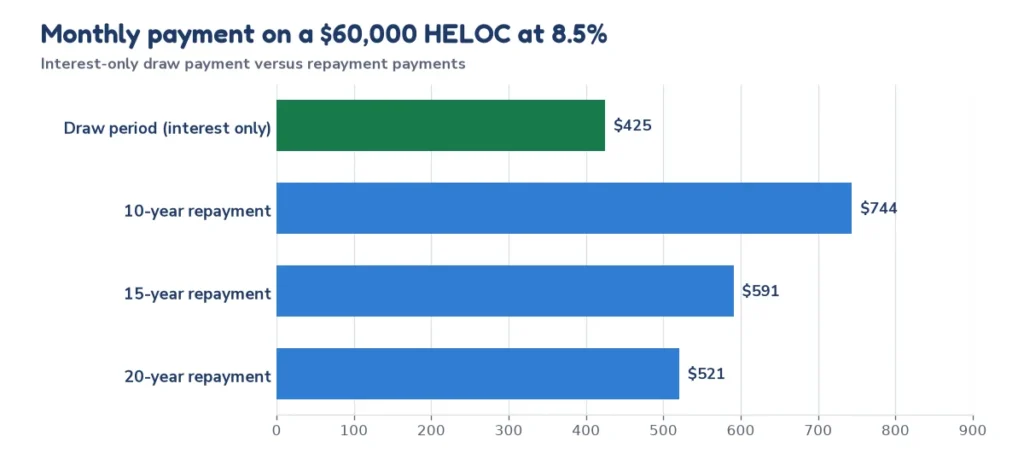
The FTC says that during the draw period you may only have to pay the interest on the money you borrowed. As a HELOC interest only payment calculator, the tool multiplies the balance by one-twelfth of the annual rate. On $60,000 at 8.5% that is $60,000 × 0.085 ÷ 12 = $425.00 a month, and none of it reduces the balance.
That is the reason the payment can look cheap and then jump. The same $60,000 over a 20-year repayment period is $520.69 a month, which is $95.69 more, and over 10 years it is $743.91.
HELOC repayment calculator: the payment after the draw period
Use the HELOC repayment calculator mode to see the payment once borrowing stops. The CFPB warns that in some cases you may have to pay back the whole amount you borrowed as soon as the repayment period begins, so check your agreement for a balloon payment before you borrow. If you have a $60,000 balance, the repayment length changes both the payment and the interest.
| Repayment period | Monthly payment | Interest in repayment |
|---|---|---|
| 5 years | $1,230.99 | $13,860 |
| 10 years | $743.91 | $29,270 |
| 15 years | $590.84 | $46,352 |
| 20 years | $520.69 | $64,967 |
| 25 years | $483.14 | $84,941 |
What happens if the rate rises?
The FTC says HELOCs typically have a variable APR, and the CFPB says the payments may change from month to month. The calculator's rate table adds one, two and three points to your rate. For a $60,000 balance with a 10-year draw and a 20-year repayment, the numbers move like this:
| Rate | Draw payment | Repayment payment | Total interest |
|---|---|---|---|
| 8.5% | $425.00 | $520.69 | $115,967 |
| 9.5% | $475.00 | $559.28 | $131,227 |
| 10.5% | $525.00 | $599.03 | $146,767 |
| 11.5% | $575.00 | $639.86 | $162,566 |
Some HELOCs let you convert part of the balance to a fixed rate. The CFPB says the fixed rate is usually higher than the variable rate but is also more predictable.
HELOC or home equity loan?
| Feature | HELOC | Home equity loan |
|---|---|---|
| How you borrow | Revolving line you draw on during the draw period | Lump sum up front |
| Rate | Typically variable | Typically fixed |
| Payments | Often interest-only first, then principal and interest | Equal monthly payments over a fixed term |
| Pay interest on | Only the amount you borrow | The whole loan |
| Best for | Costs spread over time, such as projects | One known cost, such as a single purchase |
These differences come from the FTC's guide to home equity loans and lines of credit. A home equity loan is also secured by your home, and the FTC says your lender can foreclose on your home if you do not repay either one as agreed.
Costs, freezes and risks to know about
- Fees: the FTC says lenders must disclose charges to open, use or maintain the account, such as an application fee, annual fee or transaction fee, and extra charges such as an appraisal, a credit report or attorneys' fees.
- Freezes: the FTC says a lender may freeze or reduce your line if the home's value declines significantly below the appraised amount or if your financial circumstances change materially.
- Your home is the collateral: the CFPB says that if you fall behind or cannot repay on schedule, you could lose your home.
- Right to cancel: the FTC explains that you have three days to cancel a home equity line secured by your primary home.
Interest-rate APRs on HELOCs are based on interest alone and do not include points and other financing charges, according to the FTC, so compare total cost and not just the quoted rate.
Example: planning a ,000 renovation with the HELOC calculator
A homeowner with a $450,000 home and a $260,000 mortgage wants $60,000 for a kitchen. First the HELOC calculator limit mode shows that an 80% limit allows $100,000, so a $60,000 line fits inside it with room to spare. Equity left after drawing the full $100,000 would be $90,000, and after the $60,000 it is $130,000.
Next the payment mode shows what the line costs. At 8.5% the interest-only payment is $425 a month for 10 years, and the repayment payment is $520.69 a month for 20 years. If the rate climbs three points to 11.5%, the same balance costs $575 interest-only and $639.86 in repayment. The right question is whether the higher figures still fit your budget, and not only whether today's payment does.
Questions to ask a lender about a HELOC
| Ask about | Why it matters |
|---|---|
| The combined loan-to-value limit | It sets the largest line you can get |
| The index, margin and rate cap | It decides how far a variable rate can climb |
| The length of the draw period | It sets when payments start to include principal |
| What happens at the end of the draw period | Some plans require the whole balance at once |
| Fees to open, use and keep the line | Application, annual and transaction fees add to the cost |
| Whether you can lock part of the balance at a fixed rate | It makes payments more predictable |
Before you borrow, the closing cost calculator shows the cash you need to buy a home, including closing costs.
Frequently asked questions
10 quick answers
How much can I borrow with a HELOC?
Multiply your home value by the lender's combined loan-to-value limit and subtract your mortgage balance. At 80%, a $450,000 home with a $260,000 mortgage supports a $100,000 line. Your lender confirms the limit.
How is a HELOC payment calculated?
During the draw period it is often interest only: balance times the annual rate divided by 12. In the repayment period it is a standard loan payment based on the balance, rate and number of months.
What is the draw period on a HELOC?
It is the period when you can borrow from the line. The CFPB gives 10 years as an example. After it ends you can no longer borrow and the repayment period begins.
How long is the repayment period?
The CFPB says lenders often set repayment over ten or 20 years. Some plans require the whole balance at once, so read the agreement.
Is a HELOC rate fixed or variable?
Usually variable, according to the FTC and CFPB, so payments can change. Some lenders let you convert part of the balance to a fixed rate, which is usually higher.
Why does my HELOC payment go up?
At the end of the draw period you start repaying principal as well as interest, and the CFPB notes the monthly payments are often significantly higher. A variable rate can also raise the payment.
Can a lender freeze my HELOC?
The FTC says a lender may freeze or reduce the line if the home's value falls significantly below the appraised amount or if it reasonably believes you cannot make your payments because of a material change in your finances.
Is a HELOC the same as a home equity loan?
No. A HELOC is a revolving line with a typically variable rate. A home equity loan is a lump sum, typically at a fixed rate, with equal payments over a set term.
What happens if I cannot pay?
Both are secured by your home. The FTC says the lender can foreclose if you do not repay as agreed.
Does this calculator show my exact payment?
No. It is an estimate based on the numbers you enter and a constant rate. Your lender's disclosures show the exact terms, fees and rate caps.
Related calculators
- Mortgage calculator for payments, taxes and insurance
- Loan calculator for any fixed-rate loan
- Compound interest calculator for growth and savings
- Simple interest calculator for one-period interest
- Car loan calculator for vehicle payments
- All free calculators
Sources and further reading
- Consumer Financial Protection Bureau: What is a home equity line of credit (HELOC)?: equity, draw period, repayment period and variable rates
- Federal Trade Commission: Home Equity Loans and Home Equity Lines of Credit: costs, freezes, foreclosure and your right to cancel
- CFPB: What You Should Know About Home Equity Lines of Credit: the federal consumer booklet on HELOCs
This page is general information and not financial advice. Last reviewed: October 2026.