How to get rid of PMI: on a conventional loan you can ask your servicer to cancel private mortgage insurance once the balance reaches 80% of the home’s original value, and it must end automatically at 78%. On a $400,000 home bought with 10% down at 7.40%, that takes 8 years 9 months by request or 10 years automatically, unless you pay extra. Here are all the ways to remove PMI sooner, and how FHA mortgage insurance differs.
When does PMI go away? The three rules
- Request at 80%: you can ask in writing to cancel PMI when the balance is scheduled to reach, or you pay it down to, 80% of the original value. You need a good payment history, no second liens, and you may need to show the home has not lost value.
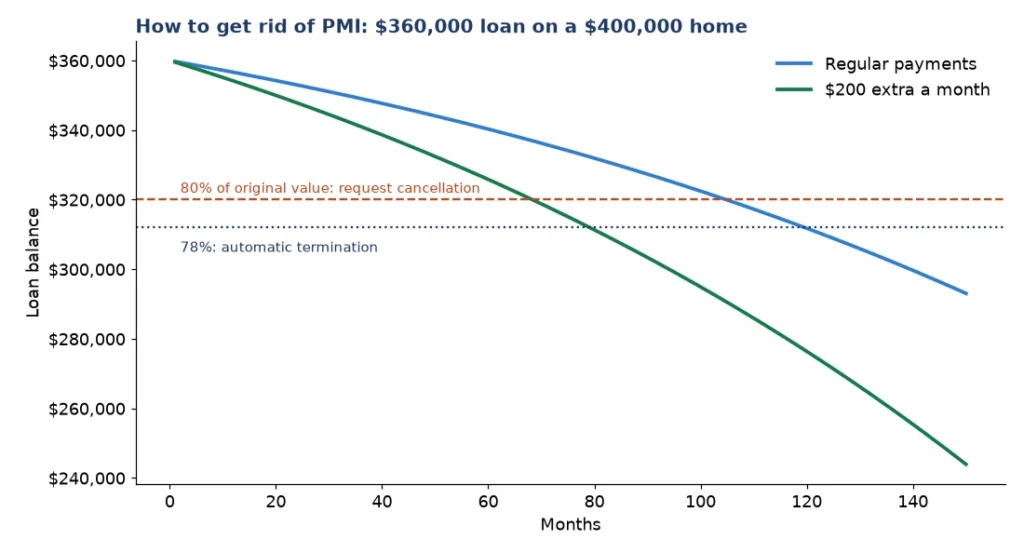
- Automatic at 78%: the servicer must end PMI on the date the balance is scheduled to reach 78% of the original value, if you are current. Extra payments do not move this automatic date, so ask at 80%.
- Midpoint: PMI must end the month after the loan reaches the middle of its term, 15 years on a 30-year loan, even if the balance is higher.
“Original value” usually means the lower of the purchase price or the appraisal when you bought. These rules come from the Homeowners Protection Act and do not apply in the same way to loans classed as high risk.
Example: how long until PMI comes off
| Plan | PMI can be cancelled after | PMI paid (at $150 a month) |
|---|---|---|
| Regular payments, request at 80% | 8 years 9 months | $15,750 |
| Regular payments, automatic at 78% | 10 years | $18,000 |
| $200 extra a month, request at 80% | 5 years 9 months | $10,350 |
| $500 extra a month, request at 80% | 3 years 10 months | $6,900 |
$360,000 loan on a $400,000 home, 30-year fixed at 7.40%. PMI of 0.5% of the loan a year is an example; your rate depends on credit score and down payment.
Ways to remove PMI sooner
- Pay extra principal and ask to cancel as soon as the balance hits 80% of the original value.
- A new appraisal: if your home has risen in value, some servicers will cancel PMI based on current value, often after you have held the loan for a set time. Ask for their rules first, since you usually pay for the appraisal.
- Refinance into a loan of 80% or less of the current value. Only worth it if the new rate and closing costs make sense; the refinance calculator shows the break-even.
- Recast after a lump sum: the balance drops, which can bring you to 80% sooner. See mortgage recast vs refinance.
FHA mortgage insurance is different
- FHA loans charge an upfront premium and an annual mortgage insurance premium (MIP), not PMI. For most new FHA loans since March 20, 2023, the annual MIP is 0.55% of the loan.
- With less than 10% down, annual MIP generally lasts for the life of the loan; with 10% or more down, it ends after 11 years.
- The usual way out of FHA MIP is to refinance into a conventional loan once you have 20% equity.
Steps to cancel PMI
- Find the 80% date on your PMI disclosure or ask your servicer.
- Check your balance: original value × 0.80 is the target.
- Send a written request to the servicer, and ask what proof of value it needs.
- Keep paying on time; late payments can delay cancellation.
- Check your next statement to make sure the PMI line is gone.
Track the date with the amortization schedule calculator. If you are still buying, see how much down payment for a house for ways to avoid PMI from the start.
These examples explain the math for planning. They are general information, not financial advice; your lender’s Loan Estimate gives the real figures.
Related calculators and guides
- Mortgage calculator with PMI
- Amortization schedule calculator
- Refinance calculator
- how much down payment for a house
- paying off your mortgage early
Sources
- When can I remove PMI from my loan? (CFPB): 80%, 78% and midpoint rules
- Bulletin 2015-03, PMI cancellation and termination (CFPB)
- Mortgagee Letter 2023-05, annual MIP reduction (HUD): annual MIP 0.55%
- Monthly mortgage insurance premium calculation (HUD)
- Primary Mortgage Market Survey (Freddie Mac)
Frequently asked questions
5 quick answers
How do I get rid of PMI?
Ask your servicer in writing once your balance reaches 80% of the original value; it ends automatically at 78% or at the loan’s midpoint. Paying extra or refinancing can get you there sooner.
When does PMI automatically go away?
When the balance is scheduled to reach 78% of the original value, if you are current, or at the midpoint of the loan term.
Can I remove PMI if my home value went up?
Possibly. Some servicers allow cancellation based on a new appraisal; ask for their requirements.
Does FHA mortgage insurance go away?
Only after 11 years if you put 10% or more down; otherwise it generally lasts for the life of the loan unless you refinance.
Is PMI worth paying to buy sooner?
It can be, if waiting to save 20% would take years. See the down payment guide for the trade-off.
Did you like this?
Last updated: