Should I refinance my car? Yes, if a new loan lowers your rate enough that the savings beat the fees, and you keep the same number of months or fewer. A lower rate on the same term is a clear win. A longer term with a lower payment can cost you more in the end, so check the total, not just the monthly payment.
Should I refinance my car? The quick test
| Question | Good sign | Warning sign |
|---|---|---|
| Is the new rate lower? | Clearly lower than your current rate | Only slightly lower |
| How many months? | Same or fewer months than you have left | More months than you have left |
| Fees | Small, repaid by the savings in a few months | Large, or a prepayment penalty on the old loan |
| Total cost | Total of remaining payments goes down | Total goes up even if the payment drops |
| The car | Worth more than you owe | You owe more than it is worth |
Car refinance: a worked example
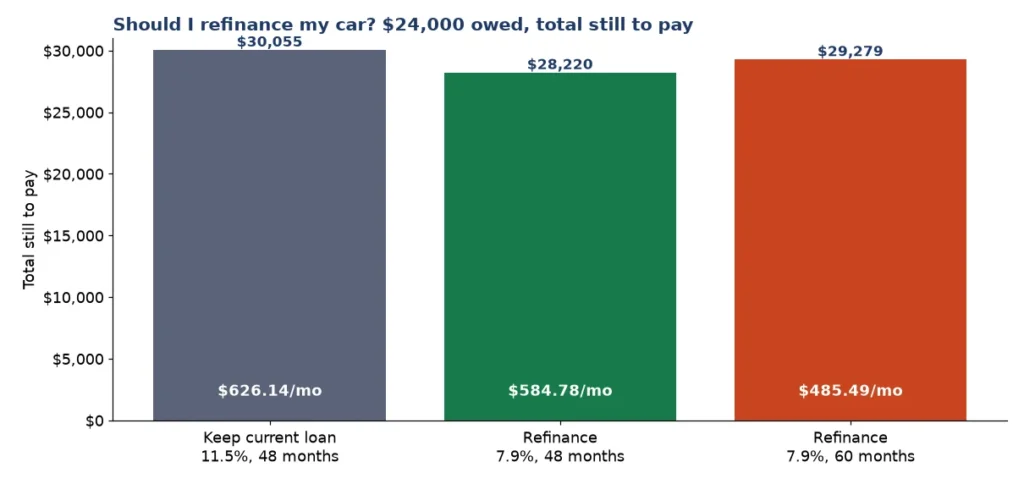
Say you owe $24,000 at 11.5% with 48 months left, so you pay $626.14 a month. A credit union offers 7.9% for 48 months, and you pay $150 in fees (for example a title or lien transfer; check your state’s fee).
| Current loan | Refinanced, 48 months | Refinanced, 60 months | |
|---|---|---|---|
| Rate | 11.5% | 7.9% | 7.9% |
| Monthly payment | $626.14 | $584.78 | $485.49 |
| Interest still to pay | $6,055 | $4,070 | $5,129 |
| Total still to pay, with fees | $30,055 | $28,220 | $29,279 |
On the same 48 months, refinancing saves $41.35 a month and $1,835 in total; the fee is repaid in 4 months. Stretching to 60 months makes the payment even lower ($485.49), but you pay for 12 more months, so the total saving shrinks to $775.
How much does each rate save?
The same $24,000 and 48 months at different new rates, with a $150 fee:
| New rate | Payment | Monthly saving | Total saving |
|---|---|---|---|
| 11.5% | $626.14 | $0.00 | $0 |
| 10.0% | $608.70 | $17.43 | $687 |
| 9.0% | $597.24 | $28.90 | $1,237 |
| 8.0% | $585.91 | $40.23 | $1,781 |
| 7.0% | $574.71 | $51.43 | $2,318 |
| 6.0% | $563.64 | $62.50 | $2,850 |
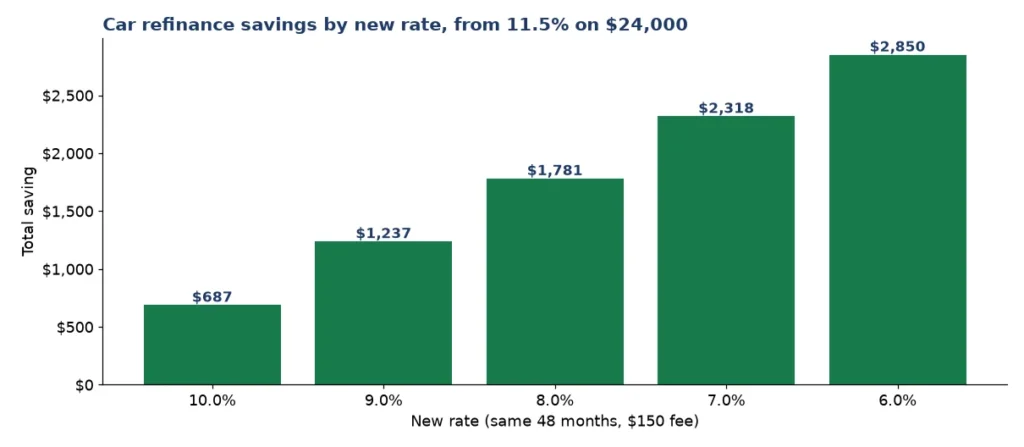
Even a drop of 1.5 points saves several hundred dollars on this loan. On a smaller balance or with only a year left, the saving may not be worth the paperwork.
Is it worth refinancing a car? When it pays
- Your credit score has improved since you bought the car.
- You took dealer financing at a high rate and a bank or credit union now offers less.
- Rates in general have fallen since your loan started.
- You want to remove or add a co-borrower.
When not to refinance your car
- Your loan has a prepayment penalty that eats the savings. Check your contract.
- You owe more than the car is worth. Many lenders will not refinance it, and longer terms make it worse.
- You have less than a year or two left: most of the interest is already paid.
- The only way to a lower payment is a longer term, and the total cost goes up.
What to have ready before you apply
- Your current lender’s name and a payoff amount (ask for a payoff quote; it differs slightly from the balance on your statement).
- The car’s VIN, make, model, year and mileage.
- Proof of income, such as recent pay stubs.
- Your driver’s license, proof of insurance and the vehicle registration.
With these ready, most auto refinance applications take minutes, and you can compare several quotes on the same day.
How to refinance a car loan, step by step
- Find your payoff amount, rate and months left on your latest statement or in your lender’s app.
- Check your credit report and score so you know which rates to expect.
- Get quotes from a few lenders, such as your bank, a credit union and online lenders, on the same day.
- Compare the rate, the term, every fee and the total of payments, not just the monthly payment.
- Apply with the best offer. The new lender pays off the old loan; keep paying the old one until it confirms the payoff.
So, should I refinance my car? If the new rate is clearly lower, the term is the same or shorter and the fees are repaid within a few months, the answer is usually yes. Use the car loan calculator to price each quote, and the loan calculator to compare total interest.
This guide explains the math for planning. It is general information, not financial advice; your lender’s documents give the real figures.
Related calculators and guides
- Car loan calculator
- Loan calculator
- Refinance calculator for a home loan
- Debt snowball calculator
- Budget calculator
Sources
- Auto loans (Consumer Financial Protection Bureau): shopping for an auto loan and comparing total cost
- Selected Interest Rates H.15, bank prime loan rate (Federal Reserve): the prime rate many loan rates follow
Frequently asked questions
5 quick answers
Is it worth refinancing a car for 1 percent?
Sometimes. On $24,000 over 48 months, going from 11.5% to 10.5% saves about $12 a month, roughly $560 over the loan before fees. On a small balance or a short remaining term, it may not be worth the effort.
Does refinancing a car hurt your credit?
A lender checks your credit when you apply, which can lower your score a little for a short time. Comparing offers within a short period keeps the effect small.
How soon can I refinance my car?
There is no single rule. Many lenders want the title registered in your name and a few on-time payments first. Ask each lender.
Can I refinance my car with the same lender?
You can ask, but many lenders will not lower the rate on an existing loan. Getting quotes from other lenders is usually how you find a better rate.
Should I refinance my car to a longer term?
Only if you need a lower payment and accept a higher total cost. In the example, 60 months cuts the payment but saves less overall than 48 months.
Did you like this?
Last updated: